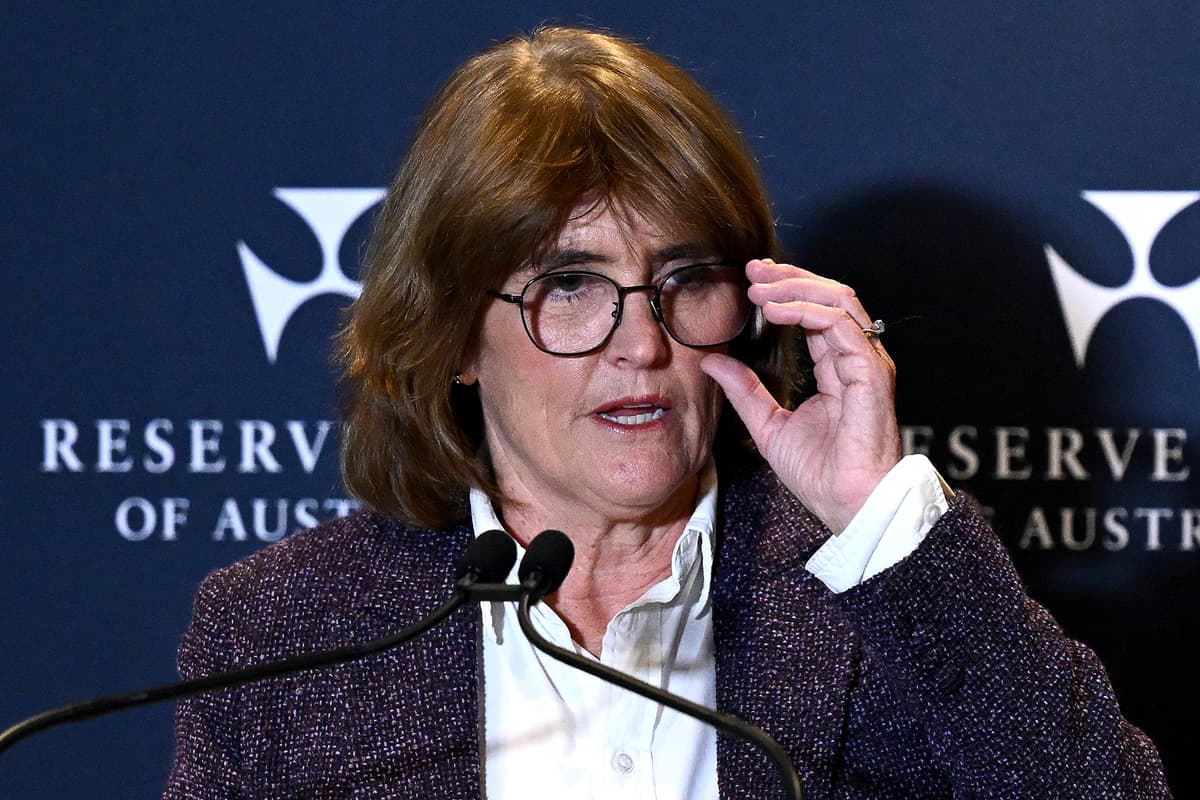
As the Reserve Bank of Australia (RBA) contemplates yet another rate rise, it is worth considering how we ended up with an economic system that means a war miles away makes housing more expensive for millions of workers. Forcing workers to pay for inflation is not uniquely Australian, but doing so through housing is particularly Australian.
Our housing system is broken. And it is breaking our macroeconomics and our politics. Australia’s broken housing system is not only driving a cost-of-living crisis, but also creating a broader crisis in economic policy with worrying political consequences. The insecurity of private rental and financial deregulation are driving insecurity across the system. It needs to be fixed.
The RBA sits at the centre of the disconnect between economic theory and cost-of-living reality. The RBA is charged with keeping inflation between 2-3%, a task it has largely failed to achieve for over a decade. That failure reflects bigger changes in the global economy, but also in Australia’s housing market.
Recently, the RBA was particularly worried by the results of a household survey that it saw showing most people misunderstand the RBA’s efforts to fix inflation. While the RBA has been steadily increasing interest rates to help fight inflation, most people see inflation and interest rates rising together.
The RBA’s concerns reflect conventional wisdom. Raising interest rates makes it more expensive to borrow, discouraging business from expanding production and consumers from borrowing and spending. Theory suggests that as spending falls, pressure on prices falls too, reducing inflation. But as Greg Jericho has pointed out, it may be the RBA, not households, who have it wrong.
The difference of views reflects an arcane change to economic data collection. It is apt that a technical change no one has heard of should capture the growing gulf between how experts analyse the world and how ordinary people live it.
In 1998, at the request of the RBA, the Australian Bureau of Statistics changed the way we measure inflation – the Consumer Price Index – to remove the cost of paying a mortgage. They had a logical reason. Raising interest rates increases mortgage costs. That meant raising interest rates directly increased CPI. And because CPI is used to determine interest rates, it created a potentially dangerous feedback loop.
The change was designed to help the public understand the Bank’s actions by making the headline CPI reported in the news the same as the information used by the Bank to set interest rates. However, the changes in measurement moved in the opposite direction to real changes in how people accessed housing, and the gulf between experts and citizens grew.
Of course, Australians have long sought to buy their own home, and for most ordinary workers that meant a mortgage. But until the 1980s, a mortgage didn’t entail the risks it does today. Loans for first home buyers were heavily regulated with fixed rates and caps. It often made it harder to get a loan but meant an increase in official interest rates had little impact on recent home buyers.
Protecting home buyers from rising interest rates is not unique to Australia. In fact, Australia now stands out internationally for the proportion of home loans on variable rates. Even in countries we think of as more ‘free market’ than Australia – like the USA or UK – most home buyers have fixed rates. When interest rates rise in America, where 30-year fixed loans are normal, home buyers barely notice.
The world was already changing in 1998, but the decision to change how CPI was measured made it harder to see what happened next. Deregulating finance wasn’t all bad news – it aided a sustained fall in interest rates. And as finance became cheap, so houses became expensive, driven in part by falling interest rates and easier to access mortgages. If everyone can borrow more, prices at auctions rise.
In the 1980s, most debt was held by businesses. Today, household debt far exceeds business debt. Household debt (overwhelmingly, mortgage debt) is now almost twice as large as business debt and, well over 100% of GDP, is amongst the highest in the world.