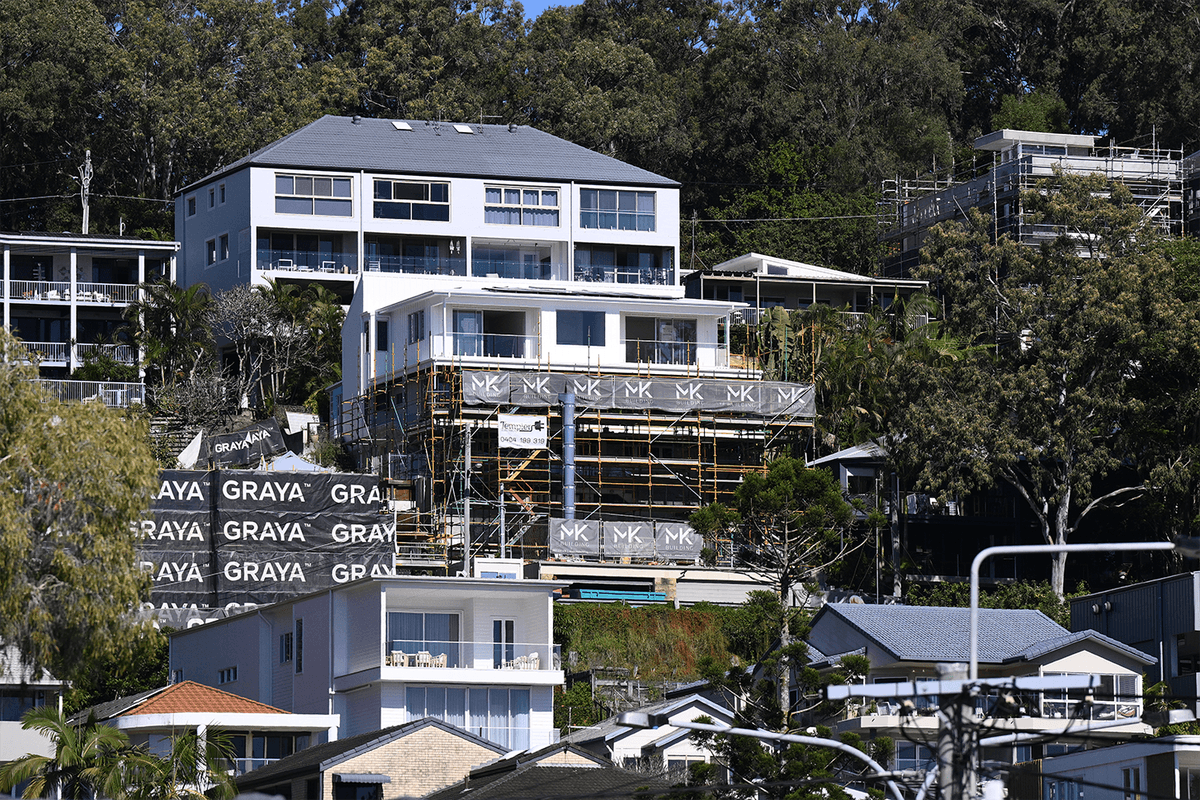
It’s hard not to miss the latest commentary around the Government’s housing tax changes and the growing claims they’re contributing to softer house prices.
My reaction? Well, of course they are. That was the point.
For years, advocates of negative gearing and capital gains tax reform argued that investor incentives were adding fuel to an already overheated market. The reforms were sold as a way to reduce speculative pressure on existing housing and improve affordability over time. If house prices are growing more slowly, flattening, or falling from previously inflated levels, then we shouldn’t be treating that outcome as some bewildering economic mystery.
But that’s exactly where much of the public discussion remains stuck.
Every month, another housing report arrives, and we’re told that tax changes are influencing investor behaviour and affecting prices. As if we’ve uncovered some startling new relationship between policy and markets.
What’s becoming increasingly frustrating is that we’re still arguing about whether these changes are having an effect rather than debating what comes next.
Because whether you supported or opposed the reforms, they are now part of the landscape.
More importantly, repeatedly threatening to reverse them if there’s a change of government creates its own problem. Housing investment depends heavily on confidence and certainty. Every election fought over the future of tax settings introduces another layer of doubt for investors, developers and institutional capital. The prospect that today’s rules might be tomorrow’s political football doesn’t encourage long-term investment. It actually discourages it.
The real question is no longer whether tax reform affects housing markets. It is whether we’re prepared to tackle the far bigger structural issues that determine housing supply and affordability in the first place.
Where is the serious conversation about the next phase of planning reform? Beyond streamlining approvals, we need to focus on the long-term structural issues that will determine whether Australia can deliver enough housing. That means investing in enabling infrastructure, unlocking well-serviced public and Crown land, and tackling the productivity challenges that continue to drive construction costs higher year after year. Modern methods of construction offer significant potential to expand industry capacity, improve efficiency and reduce costs, yet they remain underutilised. There is also considerable scope to reform the taxes, charges and regulatory settings that increasingly add to the cost of delivering new housing.
Without addressing these underlying constraints, housing affordability and supply outcomes will remain out of reach.
Get our newsletter
Quality research, analysis, explainers and factchecks from experts you can trust.
That’s where the focus should be.
And if policymakers and political parties are genuinely looking for the next phase of housing reform, they should turn their attention to the supply side, particularly Affordable Rental Housing.
If we’re serious about affordability, we need to stop talking in tens of thousands of homes and start talking in hundreds of thousands. Australia’s National Rental Affordability Scheme (NRAS) was a useful proof of concept, but the ambition was only modest. In the United States, the Low-Income Housing Tax Credit (LIHTC) has helped finance millions of affordable rental homes over several decades. The lesson isn’t to copy the model exactly, but to recognise the scale required to shift housing outcomes.
Instead of endlessly debating incentives for existing homes, why not create a more compelling framework to direct patient, long-term capital into new affordable rental housing?
The objective shouldn’t be to reshuffle ownership of existing dwellings. It should be to produce more affordable homes.
There is enormous scope to use the tax system more intelligently to encourage investment into purpose-built rental housing, affordable housing partnerships, and long-term rental supply. These are the kinds of reforms that can simultaneously improve affordability, strengthen rental security and increase housing stock where it is needed most.
That’s a far more productive debate than replaying arguments over reforms that have already been made.
Five years from now, success won’t be measured by whether investors bought a few more or a few fewer existing houses. It will be measured by whether we’ve increased affordable housing supply, lowered the cost of delivery, attracted capital into new construction and improved affordability for the people who need housing most.
We’ve spent years arguing about where investment shouldn’t go. It’s time to start discussing where it should.
Jackson Hills is CEO of National Shelter, a peak national housing body focused on secure housing for low- to modest-income householders and a healthier housing system.